The Friday Intelligence Briefing
Plain · Sourced · Every FridayThe Build BriefIssue 005
New home contract cancellations jumped 50%, and the SMSF borrowing ban starts Monday.
Cancellations of new home contracts rose 50% in June while sales for the year were up 18.4%. From Monday, self-managed super funds can no longer borrow to buy residential property. Home values fell 0.7% in July. And from July 2027, negative gearing follows new builds only.
By BuilderHQ, Melbourne
This week from the BuilderHQ team
Demand is not the problem. Conversion is.
Three sets of numbers landed this week. Each one marks a different point where a home that someone wants does not get built.
The first is finance. New home contract cancellations jumped 50% in June, which the Housing Industry Association puts down to tighter borrowing capacity and conditional finance being withdrawn. Sales across the 2025-26 financial year were still up 18.4%. People want to build. More of those projects are failing between the signature and the slab.
The second is valuation. National home values fell 0.7% in July, the largest monthly fall since December 2022, and the decline spread beyond Sydney and Melbourne for the first time. A cheaper site sounds like good news until you remember that construction lenders assess what the finished home will be worth, not what the land cost.
The third is people. New research covering more than 12,000 apprentices found that three in four have never considered leaving. The ones who do are not short of commitment. They are short of support.
One date before Monday. From 10 August, self-managed super funds can no longer borrow to buy residential property, and builders are holding thousands of signed contracts that depend on it. Details in the first signal. Last week's edition covered what a new house now costs to build.
The BuilderHQ Team
Three signals. For everyone in the build.
01 · Demand Watch
Projects are being lost after the contract is signed.
+50%
jump in new home contract cancellations, June 2026
SMSF borrowing ban starts Monday 10 August
Two measures of appetite, one measure of completion. The gap between them is the story.
| Series | Change |
|---|---|
| New home sales, 2025-26 financial year | +18.4% |
| Sales, June quarter, year on year | +4.6% |
| Contract cancellations, June on May | +50% |
The Housing Industry Association's latest New Home Sales report found cancellations of new home sales contracts jumped 50% in June compared with May. The HIA puts the increase down to higher borrowing costs limiting borrowing capacity, and to conditional finance being withdrawn.
Demand has not disappeared. Sales in the June quarter were still 4.6% higher than the same period a year earlier, and sales across the full 2025-26 financial year were up 18.4%. The monthly picture varied by state. New South Wales recorded the largest fall at 12.5%, Victoria was down 9.2% and Queensland down 3.0%, while Western Australia rose 8.1% and South Australia held steady.
That tension is the story. People still want to build. Fewer of those projects are surviving the trip from signed contract to site. More than 80% of builders now expect new home commencements to fall by at least 5%, and half expect declines of more than 10%.
What this means for you
A signed building contract is not the end of feasibility. Check that the final contract, variations, finance approval and valuation still agree before committing cash, and test the numbers early.
Late design changes can move a project outside the finance assumptions that got it approved. Cost control after planning matters as much as cost control before it.
A full sales pipeline is not the same as a secure construction pipeline. Finance readiness is worth understanding before labour and programme are committed.
Conditional approval needs to survive the final contract price. Recheck the facility whenever scope, build cost or client contribution changes.
Source: HIA New Home Sales report, June 2026; HIA survey on SMSF limited recourse borrowing arrangements, July 2026.
02 · Value Watch
A cheaper site does not automatically mean an easier build.
-0.7%
national home values, July 2026
largest monthly fall since December 2022
no change
Annual national growth is still positive at 5.3%. Over the three months to July, upper quartile values fell 3.2% while the lower price tier rose 0.3%.
| Series | Monthly change, July 2026 |
|---|---|
| Australia | -0.7% |
| Sydney | -1.4% |
| Melbourne | -1.2% |
Cotality's national Home Value Index fell 0.7% in July, accelerating from June's 0.4% decline and recording the largest national monthly fall since December 2022. Annual growth slowed to 5.3%. Sydney fell 1.4% for the month and Melbourne 1.2%, while previously stronger mid-sized markets lost momentum, with Brisbane down 0.6% and Adelaide down 0.2%. The combined regional index fell 0.2%, its first decline since January 2023.
Our second edition picked up the first behavioural signal in this story, when auction activity and clearance rates weakened. This is the next stage: softer demand now showing up in values.
The correction is concentrated at the expensive end. Over the three months to July, upper quartile values fell 3.2% nationally while the lower price tier rose 0.3%.
For residential construction, falling prices are neither automatically good nor automatically bad. A buyer may acquire a site more cheaply. But the finished property may also value lower, and construction lenders assess what the proposed home is expected to be worth once complete rather than what the land cost. Lenders describe this differently, but the principle holds across the market: the loan is sized against the completed asset. That is why a cheaper site can still produce a project that is harder to finance.
What this means for you
Use the negotiating opportunity, but rerun the project's completed value before assuming a cheaper purchase improves feasibility. A preliminary estimate is the cheapest place to test it.
A project should work against both the client's construction budget and a defensible end value. In a moving market those are different tests.
Clients can face finance pressure even when your contract price has not changed. A softer valuation can still delay or resize the job.
The on-completion valuation deserves as much attention as serviceability. A market movement can change the equity position without changing the drawings.
Source: Cotality Home Value Index, July 2026 (released 3 August 2026).
03 · Workforce
Most apprentices want to stay. The workplace decides whether they do.
76%
of current apprentices had not considered leaving
supportive workplaces cut that risk by 28%
| Series | Finding |
|---|---|
| of current apprentices had not considered leaving their apprenticeship | 76% |
| Apprentices who felt cared for and supported at work were | 28% less likely to consider leaving |
Apprenticeship Support Australia released its National First Year Experience Report on Tuesday, launched in Sydney by the Minister for Skills and Training. It draws on the experiences of more than 12,000 current and former apprentices and trainees, and it lands at a time when apprenticeship and traineeship commencements are still falling nationally.
Its most useful finding challenges a common assumption. Around 76% of current Australian apprentices said they had not considered leaving. Attrition is not mainly a commitment problem.
Where the risk changes is the early workplace experience, and the first twelve months carry the greatest risk. Apprentices who felt cared for and supported at work were 28% less likely to consider leaving. Those experiencing sadness, anxiety or worry were 65% more likely to consider leaving. Cost of living pressure is widespread, with 55% reporting they were quite or extremely affected, rising to 58% among apprentices living with disability and 60% among First Nations apprentices. Only 49% said school had given them good information about all career pathways before they started.
Organisation size shapes the experience in both directions. Apprentices in smaller workplaces often benefit from closer supervision, but retention risk rises where an employer lacks the time, systems or mentoring capacity to notice a problem early.
The Brief has covered the construction labour shortage before. This week's research gives it a second half. Recruitment is only part of the answer. Retention is capacity too, and the builders we introduce tend to be the ones who hold a team together.
What this means for you
A builder with a stable team has an operational advantage. Workforce continuity affects sequencing, workmanship and programme.
Clear, buildable documentation helps site teams at every experience level. Complexity that exists only on paper still has to be taught and executed.
Mentoring, clarity and supervision are how future capacity gets built. The research points to small, practical actions rather than large programmes.
Workforce stability affects programme reliability, which affects progress claims, facility duration and holding costs.
Source: Apprenticeship Support Australia, National First Year Experience Report, released 4 August 2026; reported by Build Australia.
From July 2027, negative gearing follows new builds. A one for one knockdown rebuild is not one.
The tax treatment of residential investment changes on 1 July 2027, and the definition of a new build is narrower than the phrase suggests. If a project completes after that date, the structure matters now.
The Government's tax package was announced in the Budget on 12 May 2026 and is now law. Two measures change how residential investment is taxed from 1 July 2027, and both turn on a single question: does the project add to the housing stock?
What changes
Negative gearing narrows to new builds. From 1 July 2027, an investor who buys an established residential property after 7:30pm on 12 May 2026 can no longer offset rental losses against salary or other income. Those losses are quarantined instead: they can be offset against residential rental income or against future capital gains from residential property, and carried forward to later years.
Properties held before the cutoff are grandfathered. Anything owned at 7:30pm on 12 May 2026, including contracts exchanged but not yet settled, continues under the existing rules until it is sold. The test is the purchase date, not the settlement date.
There is an interim window. Established properties bought after the cutoff can still be negatively geared until 30 June 2027. The restriction applies from 1 July 2027.
Capital gains tax changes too. The 50% CGT discount is replaced by cost base indexation with a minimum 30% tax rate on gains, applying to gains that accrue from 1 July 2027. Investors in eligible new builds can choose either the existing 50% discount or the new arrangement.
What counts as a new build
This is the part that decides how projects get structured, and the line is drawn around net new dwellings rather than new construction.
Generally eligible: a dwelling built on previously vacant land; a development that demolishes an existing property and replaces it with a greater number of dwellings; off the plan apartments; house and land packages; qualifying duplex developments; and newly built properties that have not previously been sold or occupied.
Generally not eligible: a knockdown rebuild that replaces one dwelling with one dwelling; substantial renovations; and granny flat additions to an existing established property.
One further limit matters for anyone building to sell. The new build treatment is available to the first investor purchaser only. A subsequent buyer of the same property does not inherit it.
Separate exemptions have been flagged for build to rent developments and for private investors participating in government housing programs, along with properties held in superannuation funds and widely held trusts. Detail on the scope of those exemptions remains limited.
Why this matters before 2027
Residential projects take time. A townhouse development that starts documentation now may not reach a first investor buyer until well after July 2027, which means the tax treatment of the finished product is being decided at design stage today.
The practical consequence is that dwelling yield has acquired a tax dimension it did not have before. One house replaced by two townhouses sits on one side of the line. One house replaced by one larger house sits on the other. That does not make the second project wrong, and plenty of owner occupier work is unaffected entirely. It does mean the question is worth asking early, particularly on infill sites where the difference between one dwelling and two is a planning decision rather than a construction one. If an investor buyer is the exit, test the numbers before the design locks.
None of this is advice about any particular project. The framework is law, the finer definition of an eligible new build is still being settled through the legislative and consultation process, and the answer for any given site depends on facts that a qualified adviser needs to look at. General information only, current at the date of publication. Seek advice specific to your circumstances.
The tax treatment of the finished product is being decided at design stage today.
What this means for you
If a project completes after July 2027 and an investor buyer is the exit, dwelling yield now carries a tax consequence. Get advice before the design locks.
On infill sites, the difference between one dwelling and two has moved from a planning question to a planning and tax question.
Knockdown rebuild and renovation work is not disadvantaged for owner occupiers. It is the investor exit that changes.
Two tax regimes will run side by side from July 2027, depending on purchase date and dwelling type. Client records need to carry the date.
Source: ATO, Tax reform: boosting home ownership, reforming negative gearing and capital gains tax; Budget 2026-27 tax reform explainer; Pitcher Partners; William Buck; Goodwin Chivas; Duo Tax.
A contract is only as strong as the scope it was signed on.
Market Watch 01 counts projects lost between signature and site. Finance explains most of them. Scope explains some, and scope is the part we can fix.
When three builders price the same house, they are rarely pricing the same scope. Each quote is honest. None is comparable. The owner signs the lowest number, and the difference surfaces later as a variation, at the point in a project where the budget has the least room left in it.
Builder C looks cheapest and is not.
Same drawings, same house, three quotes
The line: Landscaping to the rear yard
Builder A
Included as documented
Prices the work shown on the landscape plan.
Builder B
$18,000 allowance
Carries a figure, to be adjusted against actual cost.
Builder C
Not mentioned
Silent. The owner reads that as included.
Builder C looks cheapest and is not. Nobody has done anything wrong. The three quotes describe three different houses, and nothing in the paperwork tells the owner that.
Under the Standard, every builder answers the same line, one of four ways
- Included as documented
- Allowance, at a stated figure
- Excluded
- Not applicable
What the Standard does
The documents are read against a fixed schedule of the work a home requires, and every gap is settled with the client before pricing opens, so all three builders carry the same figure rather than each guessing privately.
Fair in both directions. A builder who prices carefully should not lose to a cheaper quote that is quieter about what it leaves out. An owner should not need to be a quantity surveyor to see the difference. Our Perspective on procurement sets out the argument in full.
Meet Jason Pogorelec of Inovayt, a broker who plans the finance past the settlement.
Strategy that looks past a single settlement.
Construction loans & Investment lending · West Melbourne, VIC · In the network since 2026
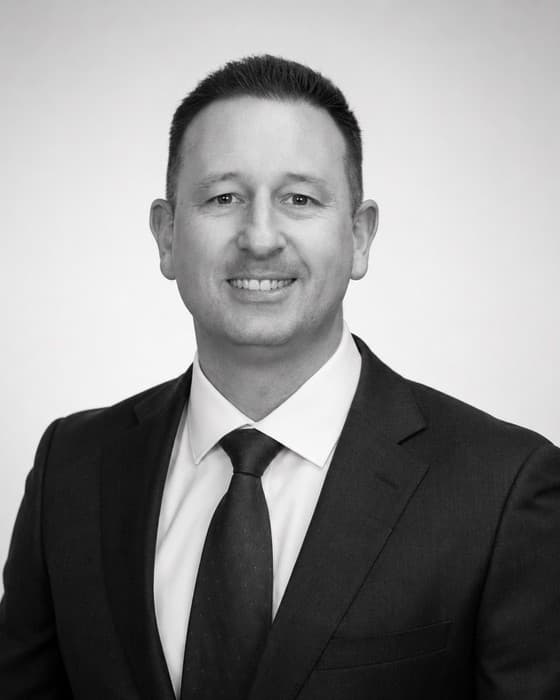
Jason Pogorelec, Senior Finance Broker
Senior finance broker · West Melbourne, VIC
5.0
Google rating, Inovayt
15+ yrs
In finance broking
9
Industry honours since 2011
Why we introduce them
This edition is about projects lost between the signed contract and the slab, and finance decides most of them. Jason Pogorelec has spent more than fifteen years in broking, all of it with one firm, and works the way that problem needs: analytical, organised, and built around a client's next decade rather than a single approval. He structures lending across home, investment, commercial and self-managed super, so that a construction loan taken today does not narrow the options tomorrow.
The practice
A senior finance broker with Inovayt in West Melbourne, working across construction loans, investment lending and self-managed super fund finance. Nine industry honours since 2011, including AFG's Top 20 Champion Broker list for Victoria in 2019 and 2020, and a finalist placing for Best Residential Broker at the 2022 Better Business Awards.
In a week where finance is what decides whether a project starts, a broker who plans past the approval is exactly who this platform exists to put in front of owners early.
Questions this edition answers
- Why are new home contract cancellations rising in Australia?
- Cancellations of new home sales contracts jumped 50% in June 2026 compared with May. The Housing Industry Association attributes the increase to higher borrowing costs limiting borrowing capacity, and to conditional finance being withdrawn. Demand itself has not fallen away: sales in the June quarter were 4.6% higher than the same quarter a year earlier, and sales across the 2025-26 financial year were up 18.4%.
- When does the SMSF borrowing ban start?
- From Monday 10 August 2026, self-managed super funds can no longer enter new limited recourse borrowing arrangements to buy residential property. Contracts exchanged before that date remain valid even if settlement occurs afterwards.
- Can an SMSF still buy residential property after 10 August 2026?
- Yes, but not with new borrowing. A fund can still buy residential property outright. Existing limited recourse borrowing arrangements are grandfathered and can still be refinanced, and borrowing for commercial and business real property is unaffected. The change applies to new residential borrowing arrangements only.
- How many building contracts are affected by the SMSF borrowing ban?
- The Housing Industry Association surveyed Australia's largest detached home builders, together representing more than 40% of national detached housing construction. On the HIA's estimate those builders hold 3,613 signed contracts backed by these arrangements that have not yet started on site, and expect 2,415 of them, close to 67%, to be cancelled. The HIA puts the effect at a 3.5% to 5% reduction in detached housing commencements nationally, and notes the figure covers detached housing only. These are expected cancellations reported by builders, not cancellations that have already happened.
- Did Australian home values fall in July 2026?
- Yes. Cotality's national Home Value Index fell 0.7% in July 2026, accelerating from a 0.4% decline in June and recording the largest national monthly fall since December 2022. Sydney fell 1.4% and Melbourne 1.2%. The combined regional index fell 0.2%, its first decline since January 2023. Annual national growth slowed to 5.3%.
- Does a cheaper site make a construction loan easier to get?
- Not necessarily. Construction lenders assess what the proposed home is expected to be worth once complete, rather than what the land cost. If values are falling, the completed property may also value lower, which can change the equity position without anything changing in the drawings or the contract price.
- What qualifies as a new build for negative gearing from 1 July 2027?
- The line is drawn around net new dwellings rather than new construction. Generally eligible: a dwelling built on previously vacant land, a development that replaces an existing property with a greater number of dwellings, off the plan apartments, house and land packages, qualifying duplex developments, and newly built properties not previously sold or occupied. Generally not eligible: a knockdown rebuild that replaces one dwelling with one dwelling, substantial renovations, and granny flat additions to an existing established property. The treatment is available to the first investor purchaser only. The framework is law, but the finer definition is still being settled, so specific advice is needed for any particular project.
- Is a knockdown rebuild negatively gearable after 2027?
- A knockdown rebuild that replaces one dwelling with one dwelling is generally not treated as a new build, so from 1 July 2027 an investor buying it would not be able to offset rental losses against other income. Replacing one dwelling with a greater number of dwellings generally is treated as a new build. Owner occupier work is unaffected: the change applies to the tax treatment of residential investment.
- Why do most apprentices leave, and what keeps them?
- Around 76% of current Australian apprentices said they had not considered leaving, so attrition is not mainly a commitment problem. Apprentices who felt cared for and supported at work were 28% less likely to consider leaving, while those experiencing sadness, anxiety or worry were 65% more likely to. Cost of living pressure was widespread, with 55% reporting they were quite or extremely affected. The findings come from Apprenticeship Support Australia's National First Year Experience Report, drawing on more than 12,000 current and former apprentices and trainees.
- Why are three builder quotes for the same house so hard to compare?
- Because there is no common format for what a quote has to answer. One builder may price an item as documented, another may carry an allowance, and a third may not mention it at all, so three honest quotes can describe three different scopes of work. The cheapest quote is often the one that is quietest about what it leaves out, and the difference usually surfaces later as a variation.
Where this edition's numbers come from
Cancellations and the SMSF deadline
Home values
Apprentice retention
Negative gearing and capital gains tax
This edition used data and reporting from the Housing Industry Association, Cotality, Apprenticeship Support Australia, the Australian Taxation Office, the Commonwealth Treasury and Build Australia. The Build Brief is compiled by BuilderHQ, Melbourne.
What would you most like The Build Brief to help you understand?
Reply with a line. The topics readers ask about most shape where we take future editions.
Reply to the teamShare
New home contract cancellations jumped 50% in June, and the SMSF borrowing ban starts Monday. This week's Build Brief.
Contact
- Read online: builderhq.com.au
- Instagram: @builderhq_
- LinkedIn: BuilderHQ
The Build Brief is compiled by BuilderHQ, Melbourne. Read past editions at builderhq.com.au/build-brief.